The Changing Role of Stablecoins in Cross-Border Payments

Harrison Mann
,
Head of Growth

We use stablecoins to move money from one place to another.
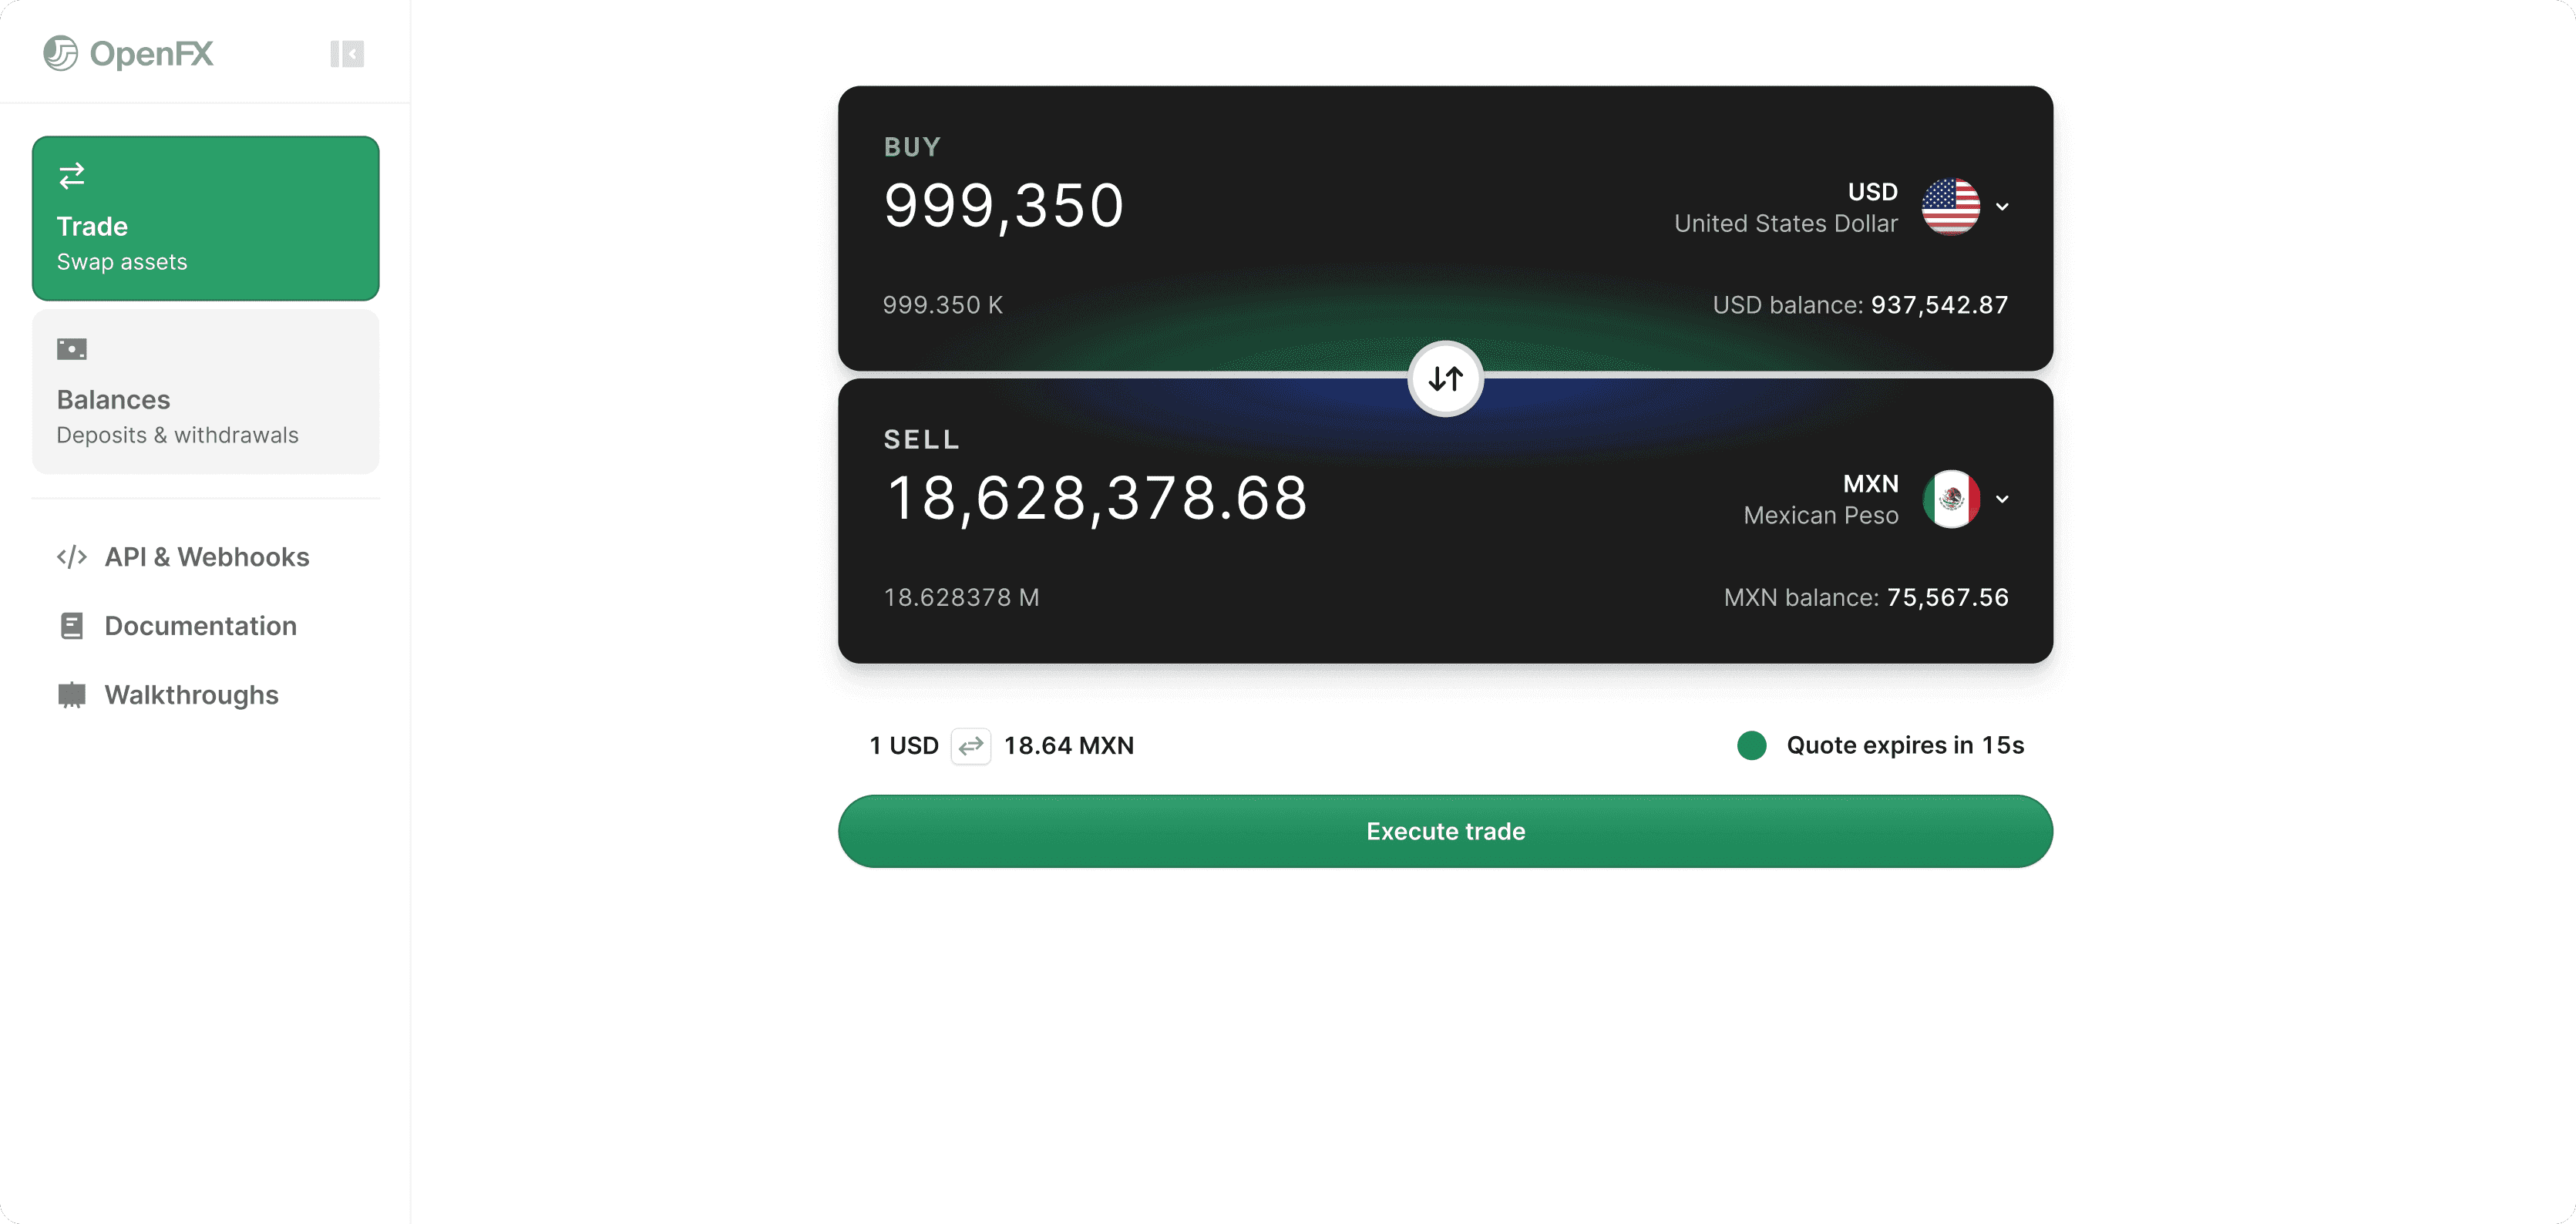
A treasurer initiates a transaction, fiat is converted into a token and then back into fiat. A dollar becomes a peso and then passes through the rest of the rails to land in our customer's accounts.
Given how much other machinery is involved in a cross-border transaction, the blockchain portion of the affair can feel almost incidental. A stablecoin is a stablecoin right, and a stablecoin is--
Exactly what is a stablecoin?
Simply, it's a blockchain token pegged to the price of an underlying currency, one that is designed to hold that peg. How that happens depends on the issuer, but the goal remains the same regardless.
But those are just the mechanics, what a stablecoin is actually for has changed quite a bit over the last decade.
These changes have resulted in a market that is both increasingly dynamic and increasingly well regulated.
Welcome to 2014
Crypto was in the middle of a brutal bear market that had pushed prices of Bitcoin down by over 50%, Mt. Gox filed bankruptcy after losing nearly a million coins, regulators were chomping at the bit to stop digital assets in their tracks.
Among many, many problems, crypto-enthusiasts had a logistical one: moving tokens was easy, moving dollars was not. Traders moving between exchanges needed a way to off-ramp into fiat. The crypto market itself operated around the clock, but if you wanted spendable cash you still needed to pass through a bank.
Or did you?
Tether launched in 2014, originally called Realcoin, it entered the market with an interesting proposition, "What if we gave you dollars, but they moved like tokens?"
A trader could bypass the banks almost entirely, sell their Bitcoin for USDT and move that USDT onto whatever exchange they wanted to.
The idea caught on.
In a year that was otherwise very bad for the blockchain, this was a breath of fresh air.
Welcome to 2018
Once again we found ourselves in a crypto winter, after the highs of 2017, Bitcoin plunged nearly 80% by year's end.
ICOs, which were once seen as the herald to a new age of finance, flopped badly, being reduced to instruments only suitable for the worst kind of speculation.
This led to another round of regulatory pressure, as the SEC began to circle, investigating whether these new instruments would be better categorized as unregistered securities.
Into this blizzard came Circle in September.
Their initial pitch was that they offered a way for traders to move between exchanges and get in and out of otherwise highly volatile assets.
A very similar pitch to Tether's own.
They differentiated themselves through a difference in perspective. Rather than leaning into the Wild West atmosphere of the blockchain, they took a more institutional approach. Circle and the CENTRE consortium focused on regulated issuance, transparent reserves and operating on an open standard that other people could plug into.
They wanted to make stablecoins respectable, to become real financial infrastructure. They saw a future for stablecoins that existed beyond crypto assets. People bought in, more than 30 of them at launch.
Stablecons as seen through Circle's lens became something that institutions might actually want to build on top of, and by the time the DeFi boom came, stablecoins were being used for everything from lending to payments.
A true digital dollar, though still not something most major banks would touch.
Welcome to 2022
You may not be surprised to learn that our story begins with the crypto market suffering from yet another winter; roughly $2 trillion in market cap was wiped out by year's end. Bitcoin dropped from $47,000 all the way down to $16,500. All other major coins followed this trajectory.
Inflation was a major cause, but another can be traced back to stablecoins.
TerraUSD entered May of 2022 with a market cap of around $18 billion. Within days, it had self-destructed.
Unlike USDC and USDT that were reserve-backed, TerraUSD sought to keep its peg through maintaining a relationship with another crypto token, Luna. This relationship fell apart, leading to a run that wiped out the value of both. The resulting chaos is often cited as the reason for the 2022 winter.
This episode marked a change in the way people thought about stablecoins. A peg could only be called a peg if there was actual substance beneath it. Standing up crypto on the back of more crypto fell firmly out of favor.
Suddenly, a lot of boring questions become important:
Who was backing the token?
How were assets being held?
How could holders redeem?
How would they deal with a run?
Quality came to the fore, a very good thing for an industry that seemed to be in almost constant turmoil, it looked like things might be turning around.
Welcome to 2023
On March 10th, 2023 Silicon Valley Bank failed.
Circle held $3.3 billion in reserves with them, about 8% of their total. Without access to these funds, USDC could no longer hold its peg.
The digital dollar fell below $0.90.
Over the weekend, Circle was unable to continue its normal issuance and redemption process because banks keep banker's hours and a bank in turmoil is no different.
The Fed would call this one of the causes of the chaos that ensued. This made something clear that we talk about a lot around here, that a transaction has a lot of moving parts and cannot be reduced down to its most simple feature.
Stablecoins might let you side-step the correspondent banking network, but they still need those banks to operate.
This lesson was learned alongside another massive change in the market: interest rates.
Reserves become the business
The rapid increase in interest rates changed the game entirely for stablecoin providers. These were companies sitting on enormous pools of cash and short-term government securities, and the higher interest rates went, the more money they were able to collect.
The business then became almost self-sustaining, the coins themselves almost didn't matter when the assets backing them could generate billions.
This raised a question, if holding stablecoins generated income for the issuer, how much of that money should be passed back to the holder?
We can see an illustration of this tension when we look at Circle's relationship with Coinbase.
In the second quarter of 2026, Circle reported $324.6 million in distribution costs connected to its agreement with Coinbase, much of which was linked to the cost of USDC balances on partner platforms.
Other stablecoin issuers decided to answer this question more directly, Global Dollar Network launched USDG on the premise that it would share the money it earned with the businesses helping to distribute its coins.
By July of 2026, USDG claimed more than 150 partners and $3 billion in circulation, a drop in the bucket by the standards of USDC and USDT but more than enough to make a statement.
PayPal came at the problem from another direction. When it launched PYUSD in 2023 it already had distribution, all transactions could pass through its platforms. So rather than focusing on paying distributors, it could turn its attention to rewarding the merchants and users that held the coins, encouraging both to hold balances.
As competition heated up, stablecoins were increasingly looking like significant financial instruments, the kind that would court regulator's attention once again.
Welcome to 2025
You guessed it, crypto winter.
By now, arguments over whether or not stablecoins should exist seemed beside the point. The better question was how they might be regulated.
In July of this year, the United States passed the GENIUS Act, creating the country's first federal framework specifically for payment stablecoins. Issuers would need to maintain stable reserves, and follow specific rules on oversight and redemption.
Soon after, Stripe's Bridge launched Open Issuance. This platform offered those who wanted their own stablecoin a path to get there. Stripe would manage reserves and compliance, acting as infrastructure to burgeoning issuers.
By Stripe's own marketing, a business could launch a compliant coin in days.
The question then becomes if anyone can issue a stablecoin, why would they use yours?
The answer is increasingly tied to what exactly your coin is designed to do.
As we’ve shown, some stablecoins are built on top of existing distribution networks, others designed to reward the companies that use them. Some are embedded into particular payment infrastructure, and some are tuned for more exotic transaction types.
The market is fragmenting across use cases, but until fairly recently nearly all of those use cases were dollar dependent. Recently though, a small but notable increase in local-currency stablecoins have begun to shake things up.
The future of stablecoins
By February 2026, non-USD backed stablecoins had reached $1.2 billion in supply, an increase of about 90% from the previous year. EUR-backed coins are the most common, but coins exist for currencies ranging from the Brazilian real to the Singaporean dollar.
While it is highly unlikely that these stablecoins will make up a significant portion of the market, they do change the way certain transactions operate. If EUR-backed stablecoins exist, for example, a payment headed to Europe may not need to pass through USD, reducing the cause for the so-called triangle trade that USD-backed coins alone failed to eliminate.
There are other stablecoin-like vehicles entering the market as well. J.P. Morgan offers JPM Coin, a USD-denominated token that looks superficially like a stablecoin, but instead acts as a tokenized commercial-bank deposit, carrying a claim on J.P. Morgan rather than being connected to the public blockchain.
Meanwhile, U.S. Bank has created USBDC, a dollar-backed stablecoin with a traditional financial institution sitting as the issuer.
The lines between traditional and digital finance are continuing to blur, which we think is a great thing.
Remember the treasurer from the beginning of this article?
They don't fundamentally care whether they are using USDC or USDT or PYUSD or anything else so long as their transaction arrives on time.
Neither do we. Some of the new tokens we described will end up succeeding in their niche, some will be seen as failed experiments, maybe one or two might reach the sorts of volumes that we see with the major players today.
Given this, for a liquidity provider, choosing one coin and building your systems entirely on its back is a strange proposition.
Like the treasurer, what we care about is making sure the transaction lands.
Sometimes that will be USDT. Sometimes USDC. Increasingly, it may be something else.
Share article
Read other articles
Stay informed with our latest articles on currency launches, institutional FX trends, and global liquidity.